Table of Contents
ToggleINTRODUCTION
A divorce decree can say one spouse keeps the house. It can assign the mortgage payment to your former spouse. It can state you have no further obligation for the property.
But the mortgage lender did not sign your divorce decree.
If your name is still on the mortgage, you remain legally responsible for that debt — regardless of what your divorce agreement says. If your former spouse misses a payment, your credit suffers. If they default, the lender can pursue you. If they file for bankruptcy, you may be left holding the full balance.
This is one of the most misunderstood financial risks in divorce. Thousands of people walk away from their marriage believing the property issue is resolved, only to discover years later that a joint mortgage is still dragging down their credit, blocking them from buying a new home, or exposing them to serious financial liability.
This guide explains seven realistic options for removing your name from a mortgage after divorce, including what each option requires, what can go wrong, and when professional help is necessary.
10. QUICK ANSWER
A divorce decree does not remove your name from a mortgage. The only ways to actually remove your liability are to have the loan refinanced in your ex-spouse’s name alone, have the lender approve a formal loan assumption, sell the property and pay off the loan, or pay off the mortgage by other means. A quitclaim deed transfers ownership — but it does not remove mortgage liability. Until the loan itself is addressed, you remain legally responsible to the lender no matter what your divorce agreement states.
Why a Divorce Decree Does Not Remove Mortgage Liability
This is the single most important concept in the entire article.
When two people sign a mortgage note, they enter a contract with a lender. That contract exists independently of the marriage. A family court has authority over the divorcing spouses — it can divide property, assign payment responsibilities, and order one spouse to take specific actions. But the family court does not have authority over the lender’s contract rights.
The lender was not a party to the divorce. The lender did not agree to release anyone. The original mortgage contract remains in force.
This means:
- Both borrowers remain personally liable for the full mortgage balance.
- The lender can pursue either borrower for missed payments or default.
- Late or missed payments by either borrower appear on both borrowers’ credit reports.
- The debt counts against both borrowers when applying for new credit.
A divorce decree that says “Spouse A shall be solely responsible for the mortgage” is enforceable between the two spouses. If Spouse A fails to pay, Spouse B may have a legal claim against Spouse A for breach of the divorce agreement. But Spouse B’s credit is still damaged, and the lender can still demand payment from Spouse B.
Understanding this distinction is the foundation for every decision that follows.
The Critical Difference Between a Deed and a Mortgage
Many people — and unfortunately some professionals — confuse deed transfers with mortgage removal.
A deed is a document that transfers ownership of real property.
A mortgage (or deed of trust, depending on the state) is a loan secured by that property, creating a personal obligation to repay the debt.
These are two separate legal instruments.
Signing a quitclaim deed transferring your ownership interest to your former spouse removes you from the property’s title. You no longer own the house.
But you still owe the money.
The mortgage note you signed is a personal promise to repay the lender. Giving away the house does not give away the debt. In fact, signing away your ownership while remaining on the mortgage creates one of the worst possible financial positions: you have all the liability and none of the ownership.
This distinction matters enormously when evaluating the seven options below.
Option 1 — Refinancing Into One Spouse’s Name
What it is: The spouse keeping the house applies for a brand-new mortgage in their name only. The new loan pays off the existing joint mortgage. Once the original loan is paid off and closed, the departing spouse’s name and liability are fully removed.
Why it works: Refinancing replaces the old loan with a completely new one. The old note is satisfied. The departing spouse has no connection to the new loan.
What is required:
- The spouse keeping the house must qualify for a new mortgage independently — meaning sufficient income, credit score, and debt-to-income ratio.
- The property must appraise at a value sufficient to support the new loan.
- The departing spouse typically signs a quitclaim deed or other deed transferring ownership as part of the process.
- Closing costs must be paid (these may be negotiated as part of the divorce settlement).
How the process generally works:
- The retaining spouse applies for a mortgage with a lender.
- The lender evaluates the retaining spouse’s individual financial qualifications.
- If approved, the new loan closes, the old loan is paid off, and the departing spouse’s liability ends.
- The departing spouse should verify that the original loan shows as paid in full on their credit report.
Common mistake to avoid: Agreeing in a divorce settlement that your spouse “will refinance” without setting a firm deadline or enforcement mechanism. If no deadline is set, or the deadline is vague, you may remain on the mortgage indefinitely.
When professional help may be necessary: If your spouse claims they cannot qualify for refinancing, a mortgage professional can evaluate whether that is actually true. An attorney can help you negotiate enforceable refinancing deadlines and fallback provisions (such as a forced sale if refinancing does not occur by a specific date).
Option 2 — Formal Loan Assumption
What it is: Some mortgage loans allow one borrower to formally assume the full loan — taking over complete responsibility — while the other borrower is released by the lender.
Why it works: When a lender formally approves an assumption and releases the departing borrower, that borrower’s contractual obligation ends. The original loan continues, but with only one borrower.
What is required:
- The mortgage must contain an assumption clause, or the lender must be willing to allow an assumption. Not all loans are assumable.
- Certain government-backed loans — including FHA loans, VA loans, and USDA loans — may have assumption provisions, subject to the lender’s approval and the assuming borrower’s qualification. According to the Consumer Financial Protection Bureau’s mortgage guidance, borrowers should contact their loan servicer to understand available options.
- Conventional loans are generally not assumable unless the loan documents specifically allow it.
- The assuming spouse must typically demonstrate that they can independently handle the payment obligation.
How the process generally works:
- Contact the loan servicer and ask whether the loan is assumable.
- If so, request the assumption application and requirements.
- The assuming spouse submits a formal application.
- The servicer evaluates the assuming spouse’s qualifications.
- If approved, the servicer prepares a release for the departing borrower.
- The departing spouse should obtain written confirmation of the release and monitor their credit report.
Common mistake to avoid: Assuming that all mortgages are assumable. Most conventional mortgages originated in recent decades include a “due-on-sale” clause that prevents assumption without the lender’s consent. If the loan is not assumable, this option is unavailable.
When professional help may be necessary: If you have a VA loan, the assumption process involves additional considerations, including the veteran’s entitlement. A mortgage professional or attorney experienced with VA loans can help navigate this process.
Option 3 — Selling the Property
What it is: The house is sold, the mortgage is paid off from the sale proceeds, and both spouses are released from the loan obligation.
Why it works: When the mortgage is paid in full, the contract ends. Neither borrower owes anything further. Both names are removed from the liability.
What is required:
- Both spouses (or a court order) must authorize the sale.
- The property must sell for enough to cover the remaining mortgage balance, closing costs, and any sale-related expenses.
- If the property is “underwater” (the mortgage balance exceeds the home’s value), the shortfall must be addressed — either from other assets, a negotiated short sale with the lender, or other arrangements.
How the process generally works:
- Agree (or obtain a court order) to sell the property.
- List the property with a real estate agent or arrange a private sale.
- At closing, the mortgage is paid in full from the proceeds.
- Remaining proceeds, if any, are divided according to the divorce agreement.
- Both borrowers verify that the loan is reported as paid in full on their credit reports.
Common mistake to avoid: One spouse blocking or delaying the sale to maintain leverage in the divorce. If you are the spouse who wants to be removed from the mortgage, address the sale timeline in your divorce negotiations. Include provisions for what happens if the property does not sell within a reasonable period.
When professional help may be necessary: If your spouse refuses to cooperate with a sale, an attorney can pursue a court order. If the property is underwater, a real estate attorney or financial professional can help evaluate options such as short sales and their potential consequences (including tax implications).
Option 4 — Paying Off the Mortgage
What it is: The mortgage is paid off entirely — either from marital assets, settlement proceeds, or other funds — and the loan is closed.
Why it works: A fully paid mortgage eliminates all liability for both borrowers.
What is required:
- Sufficient liquid funds or other assets to satisfy the full remaining balance.
- A payoff statement from the loan servicer showing the exact amount needed to close the loan.
- Coordination with the divorce settlement to determine which spouse provides the payoff funds and how this affects the overall property division.
How the process generally works:
- Request a payoff statement from the loan servicer.
- Arrange for payment (this may come from the sale of other assets, retirement-account division, or liquid savings).
- Verify that the loan servicer applies the payoff correctly and closes the loan.
- Obtain a lien release or satisfaction of mortgage from the lender.
- Confirm the loan shows as paid in full on both borrowers’ credit reports.
Common mistake to avoid: Using retirement funds to pay off a mortgage without understanding the tax consequences. Early withdrawals from retirement accounts may trigger income taxes and penalties. A tax professional should review any plan that involves retirement-account funds.
When professional help may be necessary: A financial planner and tax professional can evaluate whether paying off the mortgage makes sense compared to refinancing or selling — particularly when the payoff involves retirement assets, investment accounts, or other tax-sensitive funds.
Option 5 — Negotiating a Structured Deadline in the Divorce Agreement
What it is: The divorce settlement or court order includes a specific, enforceable deadline by which the retaining spouse must refinance, assume, or otherwise remove the departing spouse from the mortgage.
Why it matters: Many divorce agreements say the retaining spouse “shall refinance” but fail to include a specific deadline, consequences for noncompliance, or fallback provisions. Without these, the departing spouse may have no practical way to force action.
What should be included:
- A specific deadline (for example, “within 180 days of the final divorce decree”).
- A consequence if the deadline is not met (for example, “the property shall be listed for sale within 30 days”).
- A provision addressing who pays refinancing costs.
- A provision addressing what happens if the retaining spouse does not qualify for refinancing.
- Language that makes the obligation enforceable through contempt proceedings or other court action.
How it works in practice:
- During divorce negotiations (or through mediation or litigation), negotiate specific mortgage-removal terms.
- Include the terms in the written settlement agreement or proposed court order.
- Ensure the terms are incorporated into the final divorce decree.
- If the deadline passes without compliance, file a motion with the court to enforce the order.
Common mistake to avoid: Accepting vague language such as “as soon as reasonably possible” or “when financially feasible.” These phrases are extremely difficult to enforce. Insist on specific dates and specific consequences.
When professional help may be necessary: A family-law attorney is critical for drafting enforceable mortgage-removal provisions. If you have already signed a vague agreement and your ex-spouse is not cooperating, an attorney can advise you on enforcement options in your jurisdiction.
Option 6 — Requesting a Lender Release (Rare)
What it is: You ask the lender to voluntarily release you from the mortgage obligation without refinancing or paying off the loan.
Why this is listed: Some people assume they can simply call the bank and ask to be removed. It is important to understand why this rarely works — and the narrow circumstances in which it occasionally might.
Reality check: Lenders have very little incentive to release a borrower. Every borrower on the note represents additional security for the lender. Removing a borrower reduces the lender’s ability to collect if the remaining borrower defaults. For this reason, most lenders will decline a release request.
When it might be possible:
- Some loan servicers have internal modification or release programs, particularly for loans that are being restructured.
- In rare cases, a lender may agree to a release if the remaining borrower has exceptionally strong financial qualifications and the loan-to-value ratio is very low.
- Some lenders have specific divorce-related processes, particularly for certain government-backed loans.
How to explore this option:
- Contact the loan servicer (not the original lender, unless they are the same entity) and ask whether they have a borrower-release or assumption process.
- Be prepared for the answer to be no.
- If the servicer is willing to consider it, ask what documentation and qualifications are required.
- Get any release in writing.
- Verify the change on your credit report.
Common mistake to avoid: Assuming silence means release. If you stop receiving statements or the servicer stops contacting you, that does not mean you have been released. Only a formal written release from the lender ends your obligation.
When professional help may be necessary: If you believe the lender has an obligation to consider a release (for example, under specific loan program rules), a mortgage professional or consumer-rights attorney can evaluate your situation.
Option 7 — Pursuing a Court Order to Compel Action
What it is: If your divorce decree requires your ex-spouse to refinance or remove you from the mortgage, and your ex-spouse has failed to comply, you may be able to return to court to enforce the order.
Why it matters: A court order that is not enforced is essentially meaningless. Courts have tools to compel compliance, including contempt findings, fines, and orders directing the sale of the property.
What is required:
- A divorce decree or settlement agreement that specifically requires your ex-spouse to take action regarding the mortgage.
- Evidence that the deadline has passed or that your ex-spouse has failed to comply.
- A motion or petition filed with the court that issued the divorce decree.
How the process generally works:
- Review your divorce decree to confirm the specific obligations and deadlines.
- Document the noncompliance (for example, showing that the mortgage still appears on your credit report or that you received no evidence of refinancing).
- File a motion for contempt or enforcement with the appropriate court.
- The court may hold a hearing and, if it finds noncompliance, may order the property sold, impose penalties, or take other action.
Common mistake to avoid: Waiting too long. The longer you remain on a joint mortgage, the greater your exposure. If your ex-spouse misses the refinancing deadline, act promptly. Each month of delay is another month of risk.
When professional help may be necessary: Court enforcement proceedings typically require a family-law attorney. The procedures, timelines, and standards for contempt or enforcement vary significantly by jurisdiction. According to the U.S. Courts information on family-law matters, family-law enforcement is generally handled through state courts, and procedures differ from state to state.
What a Quitclaim Deed Actually Does — and Does Not Do
This issue deserves its own section because the misunderstanding causes serious financial harm.
What a quitclaim deed does:
- Transfers whatever ownership interest one person has in a property to another person.
- Removes the grantor’s name from the property title.
What a quitclaim deed does NOT do:
- Remove the grantor’s name from the mortgage.
- End the grantor’s personal liability for the mortgage debt.
- Change the mortgage contract in any way.
- Notify the lender of the ownership change.
If you sign a quitclaim deed giving up your ownership but remain on the mortgage:
- You no longer own the house.
- You still owe the full mortgage debt.
- You cannot sell the house to pay off the debt (because you no longer own it).
- Your credit is still affected by any missed payments.
- The lender can still pursue you for the full balance.
This is one of the most dangerous financial positions you can be in after a divorce.
Never sign a quitclaim deed as part of a divorce without simultaneously addressing the mortgage liability. If your spouse is asking you to sign a quitclaim deed without refinancing the mortgage, understand that you are giving up your leverage while retaining your risk.
What Happens If Your Ex Stops Paying
If your name remains on the mortgage and your former spouse stops making payments:
- Late payments appear on your credit report. Most lenders report to credit bureaus for all borrowers on the account. Even one 30-day late payment can significantly damage your credit score.
- The lender can demand payment from you. You signed the note. You are personally liable. The lender does not care about your divorce decree.
- Foreclosure affects both borrowers. If the property goes to foreclosure, it appears on both credit reports and can affect your ability to obtain housing or credit for years. According to Experian’s guidance on foreclosure and credit, a foreclosure can remain on a credit report for seven years.
- Deficiency judgments may follow. In some states, if the foreclosure sale does not cover the full mortgage balance, the lender may pursue a deficiency judgment against either or both borrowers for the remaining amount.
- Your divorce decree gives you a claim against your ex — but collecting may be difficult. You can return to court and seek enforcement, but if your ex-spouse has no income or assets, a judgment against them may be uncollectible.
Practical protection: If you cannot immediately get off the mortgage, consider monitoring the loan status. Some servicers allow both borrowers to set up payment notifications. You may also set up credit-monitoring alerts so you are notified immediately if a late payment is reported.
How a Joint Mortgage Affects Your Credit and Borrowing Power
Even if your ex-spouse is making timely payments, a joint mortgage affects you in several ways:
- Debt-to-income ratio: The full mortgage payment counts as your debt obligation when you apply for a new mortgage, car loan, or other credit. This can prevent you from qualifying for new borrowing.
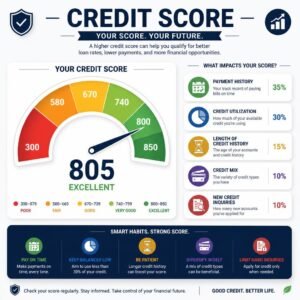
- Credit utilization and account history: The mortgage appears as an active account on your credit report. Its payment history — good or bad — affects your credit profile.
- Future home purchase: Many lenders will not approve a new mortgage if you already appear as a borrower on an existing mortgage, unless you can demonstrate that you are not the party making payments (some loan programs accept 12 months of canceled checks from the other borrower as evidence, but this is not universal).
Understanding these effects is important when deciding how urgently to pursue removal.
Decision Framework — Choosing the Right Option
| Your Situation | Most Likely Viable Option | Key Consideration |
|---|---|---|
| Ex-spouse has good credit and sufficient income | Refinancing (Option 1) | Set an enforceable deadline in the divorce agreement |
| Government-backed loan (FHA, VA, USDA) | Loan assumption (Option 2) | Contact servicer to confirm assumability |
| Neither spouse can afford the home independently | Selling the property (Option 3) | Address timeline and underwater scenarios |
| Significant liquid assets available | Paying off the mortgage (Option 4) | Evaluate tax consequences before using retirement funds |
| Divorce is not yet finalized | Structured deadline (Option 5) | Negotiate specific terms, dates, and fallback provisions |
| Loan-to-value ratio is very low, remaining borrower is very strong | Lender release (Option 6) | Unlikely but worth asking |
| Ex-spouse is violating the divorce decree | Court enforcement (Option 7) | Consult an attorney promptly |
No single option is best in every situation. The right choice depends on the loan type, your ex-spouse’s financial qualifications, the property’s equity, your divorce timeline, and your jurisdiction’s laws.
Hypothetical Examples
Hypothetical Example 1 — Refinancing Works as Planned
Maria and David divorce. Their divorce decree states David will keep the house and refinance the mortgage into his name within 120 days. David applies, qualifies, and closes on a new mortgage. The old joint loan is paid off. Maria verifies that the original loan shows as closed and paid in full on her credit report. She is free to apply for her own mortgage when she is ready.
Lesson: When the retaining spouse qualifies for refinancing and the agreement includes a clear deadline, this process can work smoothly. Maria protected herself by including a specific timeline and verifying the result.
Hypothetical Example 2 — The Quitclaim Deed Trap
James and Susan divorce. Susan’s attorney prepares a quitclaim deed, and James signs it, transferring his ownership interest to Susan. But Susan does not refinance the mortgage. Two years later, Susan loses her job and stops making mortgage payments. James — who no longer owns the home — receives a collections notice from the lender. His credit score drops significantly, and he cannot qualify for an apartment lease.
Lesson: James gave up ownership without removing his mortgage liability. He should have refused to sign the quitclaim deed until the mortgage was refinanced, or negotiated a firm refinancing deadline with a fallback provision requiring sale of the property.
Hypothetical Example 3 — Enforcing the Divorce Decree
Patricia and Robert divorce. The decree says Robert will refinance within six months. Six months pass. Robert says he “couldn’t qualify.” Patricia consults a family-law attorney, who files a motion to enforce the decree. The court orders the property sold within 90 days. The sale proceeds pay off the mortgage, and Patricia is finally released from the obligation.
Lesson: Patricia had an enforceable deadline in her decree, documented the noncompliance, and took prompt legal action. The key was not waiting years while hoping Robert would eventually act.
Hypothetical Example 4 — VA Loan Assumption
Angela and Mark divorce. They have a VA-backed mortgage. Angela contacts the loan servicer and learns the loan may be assumable. Mark applies for a formal assumption. The servicer evaluates Mark’s qualifications and approves the assumption, releasing Angela from the note. Angela also works with the VA to address her entitlement so she can use her VA benefit for a future home purchase.
Lesson: Government-backed loans may offer assumption options that conventional loans do not. The critical step is contacting the servicer to ask — not assuming the loan cannot be transferred.
Practical Checklist
Mortgage Removal After Divorce — Action Checklist
☐ Obtain a copy of your mortgage note and deed of trust (or mortgage instrument)
☐ Identify all borrowers listed on the loan
☐ Identify the current loan servicer (this may differ from the original lender)
☐ Determine the current loan balance and payoff amount
☐ Determine the current estimated property value
☐ Calculate approximate equity (value minus balance)
☐ Determine whether the loan is a conventional, FHA, VA, or USDA loan
☐ Ask the servicer whether the loan is assumable
☐ Review your divorce decree for specific mortgage-related obligations and deadlines
☐ Confirm whether a quitclaim deed has been signed — and whether the mortgage has been addressed separately
☐ Check your credit report to confirm the mortgage still appears under your name
☐ Evaluate which of the seven options is most realistic for your situation
☐ If your ex-spouse must refinance, confirm they have applied and set a follow-up date
☐ If deadlines have passed without compliance, consult a family-law attorney about enforcement
☐ Once the mortgage is resolved, verify the change on your credit report from all three bureaus
☐ Keep copies of all closing documents, release letters, or payoff confirmations
14. FAQ
1. Does a divorce decree automatically remove my name from a mortgage?
No. A divorce decree is a court order between you and your former spouse. It does not change your contract with the mortgage lender. Your name remains on the mortgage until the loan is refinanced, assumed, paid off, or the lender formally releases you.
2. Can I just call the bank and ask them to take my name off?
You can ask, but lenders almost always decline. Removing a borrower reduces the lender’s security. In rare cases, a servicer may have a release process, but approval is uncommon for conventional loans.
3. If I sign a quitclaim deed, am I off the mortgage?
No. A quitclaim deed transfers property ownership. It has no effect on the mortgage. You can sign away your ownership and still be fully liable for the mortgage debt. This is a critical distinction.
4. What if my ex-spouse was ordered to refinance but hasn’t done it?
You may be able to return to court to enforce the divorce decree. Remedies can include contempt findings, fines, or a court-ordered sale of the property. Consult a family-law attorney in your jurisdiction to understand your options and deadlines.
5. How long should I give my ex-spouse to refinance?
There is no universal rule. Common timeframes in divorce agreements range from 90 days to one year. The key is to include a specific deadline and specific consequences for noncompliance. Vague language such as “as soon as possible” is very difficult to enforce.
6. Can I refinance the mortgage myself to get my ex-spouse’s name off?
If you are the spouse keeping the house, yes — you can refinance in your name only to remove your ex-spouse. You will need to qualify independently. If you are the spouse leaving the house, you typically cannot refinance a loan on a property you do not own.
7. What happens to my credit if my ex-spouse stops paying the mortgage?
Late payments and defaults are reported for all borrowers on the loan. Your credit score can drop significantly, and a foreclosure will appear on your credit report. Your divorce decree gives you a legal claim against your ex-spouse, but it does not protect your credit from the lender’s reporting.
8. Will the mortgage affect my ability to buy a new home?
Yes, in most cases. The existing mortgage payment typically counts in your debt-to-income ratio when you apply for a new mortgage. Some loan programs may make exceptions if you can prove the other borrower has been making all payments for a specified period, but this is not guaranteed.
9. Is an FHA or VA loan easier to assume than a conventional loan?
Generally, yes. FHA and VA loans may have assumption provisions, subject to the lender’s approval and the assuming borrower’s qualifications. Conventional loans typically contain due-on-sale clauses that prevent assumption without lender consent. Contact your servicer to confirm your loan’s specific terms.
10. What if the house is underwater — the mortgage is more than the home is worth?
This complicates every option. Refinancing may be difficult because the loan-to-value ratio is too high. Selling may require a short sale (which needs lender approval) or bringing cash to closing to cover the shortfall. A short sale can have credit and tax consequences. Consult both an attorney and a financial professional in this situation. The IRS provides guidance on the tax treatment of canceled debt that may be relevant.
11. Can I be held responsible for the mortgage even if I never lived in the house?
If your name is on the mortgage note, yes. Your liability is based on the loan contract you signed, not on whether you occupied the property.
12. What should I do right now if I’m still on a joint mortgage after divorce?
Start by obtaining a copy of your mortgage note to confirm your status. Contact the loan servicer to understand your options. Review your divorce decree for any mortgage-related deadlines. Check your credit report. Then evaluate which of the seven options in this guide is most feasible — and consult a family-law attorney or mortgage professional if you need help choosing a path forward.
1 CONCLUSION
Removing your name from a mortgage after divorce is not automatic, and it is not simple — but it is essential.
The most important things to understand:
Your divorce decree does not remove your mortgage liability. Only refinancing, loan assumption, payoff, sale, or a formal lender release can accomplish that.
A quitclaim deed is not enough. Signing away ownership while remaining on the mortgage puts you in a position of maximum risk with zero control.
Enforceable deadlines matter. If your ex-spouse is supposed to refinance, your divorce agreement should include a specific date and specific consequences — not vague promises.
Time works against you. Every month you remain on a joint mortgage is another month of credit exposure, borrowing limitations, and financial risk.
Your next steps:
- Confirm whether your name is still on the mortgage by checking your loan documents and credit report.
- Identify which of the seven options is most realistic for your situation.
- If your divorce is not yet final, negotiate specific, enforceable mortgage-removal terms before you sign.
- If your divorce is final and your ex-spouse is not complying, consult a family-law attorney about enforcement — now, not later.
- Monitor your credit to catch any problems early.
This is one of the most consequential financial issues in divorce. Getting it right protects your credit, your borrowing power, and your financial independence going forward.
17. AUTHOR BIO
About DivorceProLaw.com
DivorceProLaw.com is an educational resource covering divorce, family law, financial recovery, relationships, and life after separation. Its content is designed to help readers understand complex issues and identify appropriate next steps.
18. EDITORIAL DISCLAIMER
Disclaimer: This article provides general educational information and is not a substitute for individualized legal, financial, tax, mortgage, credit, or other professional advice. Mortgage laws, divorce procedures, property laws, and lending regulations vary by state, loan type, and individual circumstances. The information in this article applies primarily to U.S.-based situations but should not be treated as applicable to any specific jurisdiction without professional verification. Consult a qualified attorney, mortgage professional, or financial advisor in your jurisdiction when your situation requires personalized guidance.
19. SOURCES & REFERENCES
- Consumer Financial Protection Bureau (CFPB) — Help for Homeowners
https://www.consumerfinance.gov/housing/housing-insecurity/help-for-homeowners/
Supports information about contacting your loan servicer, understanding mortgage options, and borrower rights during financial hardship or life changes including divorce. - U.S. Courts — Official Federal Court Information
https://www.uscourts.gov/
Supports information about the court system, the distinction between family-court authority and lender contracts, and the fact that family-law enforcement is generally handled through state courts. - Experian — How Long Does a Foreclosure Stay on Your Credit Report?
https://www.experian.com/blogs/ask-experian/how-long-does-a-foreclosure-stay-on-your-credit-report/
Supports information about the credit-report impact of foreclosure and how long negative mortgage information remains on a borrower’s credit history. - IRS — Topic No. 431, Canceled Debt — Is It Taxable or Not?
https://www.irs.gov/taxtopics/tc431
Supports information about potential tax consequences when mortgage debt is canceled, forgiven, or discharged — relevant to short sales and underwater property situations.