Table of Contents
ToggleRe-Marrying Your Ex-Spouse: 9 Legal, Financial, and Emotional Realities Nobody Talks About Before You Sign Again
Between 10 and 15 percent of divorced couples eventually reconcile and remarry each other, according to research on marital patterns. If you are considering that step, you probably already know whether you still love your ex. What you may not know is that remarrying the same person creates a legal and financial situation that is surprisingly different from your first marriage—and from marrying someone new.
Your original divorce decree divided your property, may have awarded spousal support, restructured your retirement accounts, reallocated your debts, and changed your tax status. Remarriage does not simply undo those changes. In some cases, it triggers new consequences you would never expect: the automatic termination of support payments you were counting on, the loss of certain government benefits, a reshuffling of inheritance rights, and a fresh set of financial entanglements that can be more complicated than the first.
This guide covers the nine most important realities—legal, financial, and emotional—that most people overlook before remarrying an ex-spouse. For each one, you will learn what actually happens, what you should investigate, and what steps to take to protect yourself and your family.
This is not a list of reasons to avoid remarriage. It is a practical framework for making the decision with open eyes.
10. QUICK ANSWER
Remarrying your ex-spouse is legally treated as a new marriage, not a continuation of your first one. Your previous divorce decree generally remains in effect, meaning property that was divided stays divided. However, remarriage can terminate alimony, alter beneficiary designations, change your tax situation, affect government benefits (including Social Security and military benefits), create new community- or marital-property rights, and reset inheritance rules. Before remarrying, you should review your divorce decree, consult a family-law attorney, consider a prenuptial agreement, update your estate plan, and address the specific emotional patterns that contributed to the original divorce.
Reality #1 — Your Previous Divorce Decree Does Not Disappear
One of the most common misconceptions is that remarrying your ex-spouse “reverses” or “cancels” the divorce. It does not.
Your divorce decree is a final court order. It divided assets, allocated debts, and established obligations. When you remarry the same person, you are entering a new, separate marriage. The legal slate from the first marriage was wiped by the divorce—but it was wiped according to the terms of that decree, and those terms generally stand.
What this means practically:
- Property that was awarded to your spouse in the divorce remains their separate property unless they voluntarily convert it.
- Retirement accounts that were divided by a Qualified Domestic Relations Order (QDRO) stay divided.
- Debts that were allocated to one spouse remain that spouse’s responsibility under the decree—though creditors may still pursue joint obligors regardless of what the decree says.
What to do: Before remarrying, obtain a complete copy of your divorce decree and any amendments. Review every financial provision. Understand exactly what was divided and how. If you assume everything will simply “go back to the way it was,” you may be surprised to find that tens or hundreds of thousands of dollars in assets are now legally structured differently than you expect.
Common mistake: Assuming that remarriage means you automatically regain a 50 percent interest in property your ex-spouse received in the divorce. You do not. Any sharing of that property would need to happen through a voluntary transfer, a new agreement, or the gradual creation of new marital property under your state’s laws.
Reality #2 — Spousal Support Usually Terminates Automatically
If you are currently receiving alimony (spousal support, spousal maintenance) from your ex-spouse and you remarry that same ex-spouse, your alimony will almost certainly terminate.
In the vast majority of U.S. states, remarriage of the recipient spouse automatically ends the obligation to pay spousal support—regardless of whether you are remarrying the same person or someone new. Some state statutes terminate support upon remarriage without requiring a court motion; others require the paying spouse to petition the court, but approval is essentially automatic.
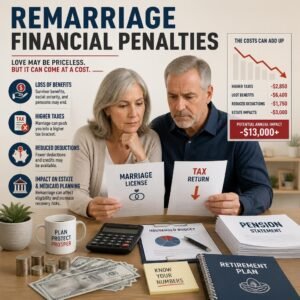
The critical financial consequence: If you were relying on $2,000 or $3,000 per month in alimony, that income disappears the moment you remarry. If the second marriage later fails, you generally cannot reinstate the alimony from the first divorce decree. That money is gone permanently.
What varies by state: A small number of states allow divorce decrees or settlement agreements to include provisions that “survive” remarriage, but this is uncommon and requires specific language in the original agreement. The American Bar Association provides an overview of family law standards and spousal support principles that may help you understand how these rules work generally.
What to do:
- Review your divorce decree to determine whether you are paying or receiving alimony.
- Determine exactly what your state law says about termination upon remarriage.
- Calculate the total financial impact of losing that income or payment obligation.
- Factor this change into your decision.
When to seek help: If spousal support is a significant part of your financial picture, consult a family-law attorney in your state before remarrying. The financial impact of this single issue can be substantial.
Reality #3 — Property Rights Reset in Ways You May Not Expect
When you remarry your ex-spouse, your new marriage creates new property rights going forward—but it does not retroactively change the property division from the divorce.
Here is what makes this complicated:
In community-property states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin, and sometimes Alaska by agreement), income earned and property acquired during the new marriage generally becomes community property. But assets each of you owned before the remarriage—including assets received in the divorce—typically remain separate property unless you commingle them.
In equitable-distribution states (the remaining states), property acquired during the new marriage is generally considered marital property subject to division if the second marriage also ends in divorce. Pre-marital assets are typically separate property, but the rules for appreciation, commingling, and transmutation vary.
The commingling trap: This is where many remarried couples make their biggest financial mistake. If your ex-spouse received a $200,000 retirement account in the divorce, and after remarriage you begin depositing new joint income into an account that is mixed with those funds, you may be converting separate property into marital property. The same applies to real estate: if your ex-spouse kept the house in the divorce and you both contribute to mortgage payments, renovations, or refinancing after remarriage, the property characterization can become complicated.
Hypothetical Example
Sarah received $150,000 from the marital home’s equity in the divorce. She used it to purchase a condo in her name only. After reconciling with her ex-husband David, they remarried. David moved into the condo, and both contributed to mortgage payments and renovations for three years. When the second marriage ran into trouble, the question arose: Is the condo still Sarah’s separate property, or has David’s financial contribution created a marital interest?
The answer depends on the state, the title, the source of funds, and whether there was a prenuptial agreement. Without clear documentation, Sarah’s separate property could become partially marital.
What to do:
- Inventory all assets each of you currently owns, including everything received in the divorce.
- Understand whether your state follows community-property or equitable-distribution rules.
- Decide in advance whether and how you will keep separate property separate.
- Consider a prenuptial agreement that specifically addresses previously divided assets.
Reality #4 — Your Tax Situation Changes Immediately
Remarriage changes your federal and state tax filing status, and this can work for you or against you depending on your income, deductions, and specific circumstances.
Filing status: You will generally file as “Married Filing Jointly” or “Married Filing Separately” for the tax year in which you remarry. If you were filing as “Single” or “Head of Household,” your standard deduction, tax brackets, and eligibility for certain credits will change.
Key tax issues to evaluate:
- Marriage penalty vs. marriage bonus: If both spouses earn similar incomes, combined filing may push you into a higher effective tax bracket. If one spouse earns significantly more, joint filing may reduce the overall tax burden.
- Alimony tax treatment: Under the Tax Cuts and Jobs Act of 2017, alimony is no longer deductible by the payer or taxable to the recipient for divorce agreements executed after December 31, 2018. If your original divorce predated this change, your alimony may have been tax-deductible. Termination of alimony upon remarriage affects the paying spouse’s deductions and the receiving spouse’s reported income. The IRS provides guidance on alimony tax treatment that explains the applicable rules depending on when your divorce was finalized.
- Dependent exemptions and child tax credits: If you share children and were splitting dependency exemptions, your remarriage may affect who claims the child and the corresponding credits.
- Capital gains on property: If you sold property as part of the divorce, or if you plan to sell property after remarriage, the capital-gains exclusion rules may be affected by your filing status.
What to do:
- Run a tax projection for both scenarios—remaining unmarried versus remarrying—before the wedding.
- Identify whether you were benefiting from a head-of-household filing status that will disappear.
- Review any alimony arrangements and the tax consequences of their termination.
When to seek help: If either spouse has significant income, owns a business, holds substantial investments, or was receiving tax benefits tied to their single or head-of-household status, consult a tax professional before remarrying.
Reality #5 — Government and Employer Benefits May Be Affected
Remarriage can affect a surprisingly wide range of benefits. Some of these changes are advantageous. Others are costly.
Social Security
If you were divorced and had been married for at least 10 years, you may be eligible to receive Social Security benefits based on your ex-spouse’s earnings record—potentially up to 50 percent of their benefit at full retirement age. Remarriage generally eliminates this option. If you remarry your ex-spouse, you would still receive spousal benefits based on your current spouse’s record (since they are the same person), but the calculation and eligibility rules apply to the current marriage. The Social Security Administration explains remarriage rules and how they affect benefits eligibility.
For individuals receiving survivor benefits (if your ex-spouse passed away), remarriage before age 60 generally disqualifies you from survivor benefits on the deceased ex-spouse’s record.
Military Benefits
Former military spouses who qualified under the 20/20/20 rule (20 years of marriage, 20 years of military service, and 20-year overlap) may lose access to TRICARE, commissary privileges, and other military benefits upon remarriage.
Medicaid and Needs-Based Benefits
Remarriage means your household income and assets now include your new spouse’s resources. If you were receiving Medicaid, Supplemental Security Income (SSI), or other means-tested benefits, your eligibility may change.
Employer Benefits
Health insurance, life insurance, and retirement-plan beneficiary designations should all be reviewed. You may gain access to your new spouse’s employer health plan—but you may also lose individual coverage advantages.
What to do:
- Before remarrying, identify every government and employer benefit you currently receive.
- Determine how remarriage affects each one.
- Calculate the dollar impact of any lost benefits.
- Factor these amounts into your overall decision.
Common mistake: Assuming you can remarry and later divorce again to “restore” benefits. Benefit restoration rules are complicated, vary by program, and do not always work the way people expect.
Reality #6 — A Prenuptial Agreement Is More Important the Second Time
Many people feel uncomfortable asking the same person they already divorced to sign a prenuptial agreement. But a prenup before a second marriage to the same spouse is arguably more important than it would have been before the first marriage.
Why?
- You already have a property division on the books. A prenup can clarify what remains separate property and what becomes new marital property.
- You may have acquired new assets, debts, businesses, or retirement savings since the divorce.
- You may have children whose inheritance rights need protection.
- You now have direct experience with how difficult and expensive an unstructured divorce can be.
What a prenup can address:
- Classification of previously divided assets
- Income and savings earned during the new marriage
- Business interests
- Retirement accounts
- Debt responsibility
- Spousal support terms if the second marriage ends
- Inheritance and estate-planning coordination
- How commingled property will be handled
What a prenup cannot do:
- Determine child custody or child support (courts always retain jurisdiction over children’s interests)
- Include terms that are unconscionable or based on fraud
- Override certain state laws (specific enforceability requirements vary by state)
What to do:
- Discuss the prenup openly and early—before setting a wedding date if possible.
- Each party should have independent legal counsel review the agreement.
- Be completely transparent about all assets, debts, and income.
- Address the specific lessons from your first marriage.
Hypothetical Example
Michael and Teresa divorced after 12 years of marriage. Their divorce decree awarded Michael his pension and Teresa the family home. After two years apart, they reconciled. Before remarrying, they signed a prenuptial agreement specifying that Michael’s pension and Teresa’s home would remain their respective separate property, and that only income earned and assets acquired during the second marriage would be considered jointly owned. When they sought couples counseling six years later to address recurring arguments about money, the prenup’s clarity actually reduced their financial anxiety and helped them focus on the emotional issues.
Reality #7 — Estate Plans and Beneficiary Designations Need Immediate Updates
Remarriage triggers important changes to your estate plan—many of which happen automatically under state law whether you intend them or not.
Spousal inheritance rights: In most states, a surviving spouse has a legal right to a minimum share of the deceased spouse’s estate (an “elective share” or “forced share”), regardless of what the will says. When you remarry your ex, they become your legal spouse again and gain these rights.
Previous wills: If you executed a will after your divorce—perhaps leaving everything to your children or a new partner—that will may be partially or fully overridden by your state’s spousal-protection statutes once you remarry. Some states have statutes that automatically revoke provisions in a will that were made before a marriage that the will doesn’t account for.
Beneficiary designations: Life insurance policies, retirement accounts (401(k), IRA, pension), and payable-on-death bank accounts pass according to beneficiary designations, not according to your will. If you changed your beneficiaries after the divorce, you need to decide whether to update them again.
Critical federal rule for retirement plans: Under federal law (ERISA), your spouse is generally the default beneficiary of your 401(k) unless they sign a written waiver. If you remarry your ex, they may automatically become your 401(k) beneficiary again—even if you designated your children or someone else after the divorce.
What to do:
- Review and update your will.
- Review and update all beneficiary designations (life insurance, retirement accounts, bank accounts).
- Review any trusts you created after the divorce.
- Consider whether a new prenuptial agreement should coordinate with your estate plan.
- Consult an estate-planning attorney, especially if you have children from the first marriage or other relationships.
Common mistake: Assuming your post-divorce will and beneficiary designations will remain effective after remarriage without any review. They often will not.
Reality #8 — Children From Your First Marriage Face New Legal Dynamics
If you and your ex-spouse have children together, remarriage does not create new custody issues in the same way that marrying a new partner might. Your children already have both biological parents in the household, which simplifies many co-parenting concerns.
However, there are still important issues to address:
Existing custody orders: Your current custody order remains in effect. If you want to modify it—for example, because you are now living together and the shared-custody schedule no longer makes sense—you will need to petition the court. Do not assume the order automatically becomes irrelevant just because you are living under the same roof again.
Child support: In many states, child support obligations terminate or may be modified upon remarriage of the parents to each other, since the purpose of child support is to ensure both parents contribute to the child’s expenses—which is assumed when they share a household. However, the existing order technically remains in effect until it is formally modified or terminated by the court.
Children from other relationships: If either of you has children from a different relationship, the remarriage creates a blended-family dynamic that can affect support obligations, inheritance rights, and custody arrangements.
Inheritance considerations: Without proper estate planning, your children could be unintentionally disinherited. For example, if you die without a will, your surviving spouse (your ex-whom-you-remarried) inherits under intestacy laws, and depending on your state, children from a prior relationship might receive less—or nothing—if the estate is small.
What to do:
- Review your existing custody and child-support orders.
- Petition the court to modify or terminate orders that no longer reflect your living arrangement.
- Update your estate plan to ensure your children are protected.
- If either spouse has children from another relationship, discuss how financial responsibilities and inheritance will be handled.
Reality #9 — The Emotional Patterns That Ended Your First Marriage Still Exist
This is the reality that receives the most attention in casual conversation but the least structured planning.
Research consistently shows that second marriages between the same partners have a higher failure rate than first marriages unless the couple actively addresses the dynamics that caused the original breakup. Remarriage to the same person does not reset the relationship. It resumes it—with all the same strengths and all the same vulnerabilities.
Patterns to examine honestly:
- Communication breakdowns (criticism, contempt, defensiveness, stonewalling—the patterns identified by relationship researcher John Gottman)
- Financial disagreements and different money values
- Unresolved trust issues, including infidelity
- Extended-family conflicts
- Parenting disagreements
- Addiction or substance-use issues
- Power imbalances
- Emotional or physical abuse (if abuse was present, remarriage without professional intervention and genuine change is high-risk)
The American Psychological Association provides research-based guidance on relationship health and factors that affect marital outcomes that can help couples assess their readiness.
What is different now? That is the essential question. If both partners can identify specific changes—in behavior, coping strategies, communication skills, financial habits, or life circumstances—the remarriage has a foundation. If the primary change is simply “we missed each other,” the core problems are likely to resurface.
What to do:
- Before remarrying, work with a licensed marriage and family therapist (LMFT) or psychologist—ideally one experienced in reconciliation dynamics.
- Identify the specific problems that caused the divorce.
- Assess whether those problems have been genuinely addressed.
- Create explicit agreements about how you will handle conflicts differently.
- Be honest about whether the desire to remarry is driven by genuine growth or by loneliness, financial pressure, children’s wishes, or fear of being alone.
Hypothetical Example
Karen and Robert divorced primarily because of chronic financial dishonesty—Robert had accumulated $40,000 in hidden credit-card debt during their first marriage. After the divorce, Robert completed a financial-counseling program and began therapy. When they began discussing remarriage two years later, their couples therapist helped them create a financial transparency agreement: monthly joint budget reviews, no individual credit accounts above a specified limit without discussion, and a shared password manager for financial accounts. They also signed a prenuptial agreement that addressed debt responsibility. Three years into their second marriage, both reported that the explicit structure—something they never had during their first marriage—was the single biggest factor in their improved relationship.
Step-by-Step: What to Do Before Remarrying Your Ex-Spouse
Step 1 — Review Your Divorce Decree Thoroughly
What to do: Obtain a complete copy of your final divorce decree, any settlement agreements, QDROs, parenting plans, and modifications.
Why it matters: Every provision in the decree continues to govern the division that already happened. You need to understand what was divided, what obligations remain, and what changes upon remarriage.
How to do it: Contact the clerk of the court that issued your divorce, or check whether your state provides electronic access to court records. If you worked with an attorney, they may have copies in their files.
What you need: Final decree, property settlement agreement, QDRO documents, custody orders, support orders, any post-decree modifications.
Mistake to avoid: Skimming the decree and assuming you remember the terms. Financial details—especially regarding retirement accounts, real estate, and debt allocation—are frequently misremembered.
When to seek help: If the decree is complex, involves significant assets, or contains terms you do not fully understand, have a family-law attorney review it with you.
Step 2 — Assess the Financial Impact of Remarriage
What to do: Create a comprehensive financial comparison: your current financial position as a single person versus your projected financial position after remarriage.
Why it matters: Remarriage can terminate alimony, change your tax bracket, affect benefits eligibility, and create new financial obligations.
How to do it:
- List your current income sources, including any alimony.
- Calculate the exact dollar amount of any alimony that will terminate.
- Run a tax projection comparing single/head-of-household filing to married filing.
- Identify all government benefits you currently receive and research whether remarriage affects them.
- List all assets and debts each of you currently holds.
- Estimate the net financial gain or loss from remarriage.
What you need: Recent tax returns, pay stubs, benefit statements, Social Security statements, insurance policies, bank and investment account statements, credit reports.
Mistake to avoid: Focusing only on the emotional decision and ignoring a potential loss of $20,000 or $30,000 or more per year in alimony or benefits.
When to seek help: Consult a financial planner or CPA if the financial stakes are significant—especially if alimony, retirement benefits, or government benefits are involved.
Step 3 — Investigate State-Specific Legal Requirements
What to do: Research the remarriage requirements in the state where you plan to marry.
Why it matters: You will need a new marriage license. Some states impose waiting periods after divorce before either party can remarry. A few states require additional steps.
How to do it: Contact your county clerk’s office or check the state’s official website for marriage-license requirements.
What you need: Identification documents, your divorce decree (some states require proof that the prior marriage was legally dissolved), applicable fees.
Mistake to avoid: Assuming you can simply “resume” the marriage without a new license and ceremony. Legally, you cannot. You must comply with the same requirements as any new marriage.
Step 4 — Negotiate and Execute a Prenuptial Agreement
What to do: Discuss a prenuptial agreement with your ex-spouse before the wedding.
Why it matters: A prenup provides a clear framework for property classification, debt responsibility, and financial expectations. Given that you have already experienced one divorce, a prenup reduces the risk and cost of a potential second one.
How to do it:
- Each party should hire an independent attorney.
- Both parties must fully disclose all assets, debts, and income.
- The agreement should specifically address previously divided property, new marital property, and debt responsibility.
- The agreement should be signed well in advance of the wedding (not the day before—this can create enforceability issues in some states).
What you need: Complete financial disclosure from both parties, independent legal counsel for each party.
Mistake to avoid: Viewing the prenup as a sign of distrust. It is a financial-planning tool. You have already experienced what happens without one.
Step 5 — Update Your Estate Plan and Beneficiary Designations
What to do: Review and update your will, trusts, powers of attorney, health-care directives, and all beneficiary designations.
Why it matters: Remarriage automatically changes your spouse’s legal rights to your estate. Outdated beneficiary designations can override your will and send assets to the wrong person.
How to do it:
- Review your current will and any trusts.
- Contact each financial institution (retirement plans, life insurance, bank accounts) and review beneficiary designations.
- Update designations to reflect your current intentions.
- Consider whether your prenuptial agreement and estate plan need to be coordinated.
- Consult an estate-planning attorney if you have children, significant assets, or complex family dynamics.
What you need: Current will, trust documents, beneficiary designation forms from every financial account, life insurance policies.
Mistake to avoid: Updating your will but forgetting to update beneficiary designations. Beneficiary designations on retirement accounts and life insurance policies typically override whatever your will says.
Step 6 — Address the Emotional Foundation
What to do: Before remarrying, engage in structured work—individually and as a couple—to assess whether the conditions that caused your divorce have genuinely changed.
Why it matters: The statistical reality is that remarriages to the same partner fail at a higher rate unless the couple has addressed the root causes of the first divorce. Love and desire alone are not sufficient indicators of long-term success.
How to do it:
- Each partner should consider individual therapy to address personal contributions to the first divorce.
- Engage in pre-marital or reconciliation-focused couples counseling.
- Create explicit agreements about how key conflict areas (finances, communication, parenting, trust) will be handled differently.
- Set a timeline: consider living together or dating for a minimum period before remarrying to test whether new patterns hold under daily-life stress.
Mistake to avoid: Rushing the remarriage because it feels exciting or because children are pressuring you. Speed was probably not the problem in your first marriage—but failing to address what was the problem almost certainly contributed.
When to seek help: If there was any history of domestic violence, addiction, infidelity, or financial abuse, professional guidance is essential—not optional—before remarriage.
Step 7 — Handle the Administrative and Legal Logistics
What to do: Complete the formal steps required to establish your new marriage and adjust all legal and financial accounts accordingly.
Why it matters: Your new legal status affects taxes, insurance, benefits, property ownership, and financial liability. Failing to update records promptly can cause administrative problems, missed benefits, or unintended legal consequences.
How to do it:
- Obtain a new marriage license and comply with your state’s ceremony requirements.
- Decide whether either spouse will change their legal name and, if so, update Social Security records, identification documents, bank accounts, and other records.
- Notify insurance providers, employers, and benefits administrators.
- Update joint account ownership and signatory authority as appropriate.
- File your taxes under the correct status for the year of remarriage.
- If you have an existing custody or support order, petition the court for appropriate modifications.
What you need: Marriage license, identification, Social Security cards, employer benefits enrollment forms, insurance policy documents, court filing forms for custody/support modifications.
Mistake to avoid: Failing to petition the court to modify or terminate outdated custody and support orders. Even if you are living together, an old order technically remains enforceable until the court changes it.
Decision-Support Table: Key Issues Before Remarrying Your Ex-Spouse
| Issue | What may happen | What to investigate | Professional who may help |
|---|---|---|---|
| Alimony termination | Payments end automatically upon remarriage in most states | Divorce decree terms; state statute on alimony termination | Family-law attorney |
| Property classification | Previously divided assets remain separate; new acquisitions may become marital property | State property laws; commingling risks | Family-law attorney; financial planner |
| Tax filing status | Changes from single/HOH to married filing jointly or separately | Tax projections for both scenarios | CPA or tax professional |
| Social Security benefits | Ex-spouse benefits may be lost upon remarriage | Benefit amount based on ex’s record vs. own record | Social Security Administration; financial planner |
| Estate and inheritance | Surviving-spouse rights activate; old wills may be partially overridden | Current will; beneficiary designations; state elective-share law | Estate-planning attorney |
| Prenuptial agreement | Protects separate property and clarifies financial expectations | Each party’s full financial disclosure | Independent attorneys for each spouse |
| Children and custody | Existing orders remain in effect until modified | Current custody order; current support order | Family-law attorney |
| Emotional readiness | Unaddressed patterns may cause a second divorce | Honest assessment of what has changed | Licensed therapist or counselor |
| Health and government benefits | Medicaid, SSI, military benefits may change | Current benefit eligibility; household income thresholds | Benefits counselor; attorney |
13. PRACTICAL CHECKLIST
Before-You-Remarry-Your-Ex Checklist
Legal and Financial
☐ Obtain and thoroughly review your final divorce decree and all related orders
☐ Identify whether alimony will terminate upon remarriage and calculate the financial impact
☐ Research your state’s remarriage waiting period and marriage-license requirements
☐ Run a tax projection comparing your current filing status to married filing
☐ Inventory all assets and debts each spouse currently holds
☐ Discuss and negotiate a prenuptial agreement with independent legal counsel for each party
☐ Review Social Security benefit eligibility under both scenarios (single vs. remarried)
☐ Investigate the impact on any government benefits (Medicaid, SSI, military benefits, etc.)
☐ Review all beneficiary designations (retirement accounts, life insurance, bank accounts)
☐ Update your will, trusts, powers of attorney, and health-care directives
☐ If applicable, petition the court to modify or terminate existing custody and support orders
☐ Notify employers, insurance providers, and benefits administrators after the marriage
Emotional and Relational
☐ Identify the specific reasons your first marriage ended
☐ Assess honestly whether those issues have been addressed with concrete behavioral changes
☐ Complete pre-marital or reconciliation counseling with a licensed therapist
☐ Create explicit agreements for handling recurring conflict areas
☐ If domestic violence, addiction, or abuse was present, obtain professional guidance before proceeding
☐ Discuss financial transparency expectations and create a shared budgeting plan
☐ Allow sufficient time living together or dating to test new patterns before remarrying
14. FAQ
1. Do I need a new marriage license to remarry my ex-spouse?
Yes. Your divorce legally ended your previous marriage. Remarrying the same person requires a new marriage license and compliance with your state’s marriage requirements, just as if you were marrying someone new.
2. Does remarrying my ex-spouse undo our divorce settlement?
No. Your divorce decree remains a final court order. Property that was divided stays divided. Debts that were allocated remain allocated under the decree’s terms. Remarriage creates new marital rights going forward but does not retroactively reverse the prior division.
3. Will I lose my alimony if I remarry my ex?
In most states, yes. Alimony typically terminates upon the recipient’s remarriage, regardless of who the new spouse is. And once terminated, it generally cannot be reinstated if the second marriage fails.
4. Should we get a prenuptial agreement before remarrying each other?
Strongly consider it. A prenup clarifies which assets remain separate, how new assets will be treated, and what happens if the second marriage ends. Given that you have already experienced one divorce, a prenup provides critical financial clarity.
5. How does remarrying my ex affect my Social Security benefits?
If you were receiving or eligible for benefits based on your ex-spouse’s earnings record (available after 10-plus years of marriage followed by divorce), remarriage generally changes the calculation. Since you are remarrying the same person, you would receive spousal benefits based on the current marriage—but you should verify the specific impact with the Social Security Administration.
6. What happens to our children’s custody order when we remarry?
The existing custody order remains in effect until formally modified by the court. Even if you are living together, petition the court to adjust the order to reflect your new living arrangement. This protects both parents if circumstances change again.
7. Do we automatically share property again once we remarry?
Not automatically for property acquired before the remarriage. Property each spouse owned before the second marriage is generally considered separate property. However, income earned and assets acquired during the new marriage may become marital or community property depending on your state’s laws.
8. How does remarriage to my ex affect my taxes?
Your filing status changes. You will file as married (jointly or separately). This may increase or decrease your tax obligation depending on your combined incomes, deductions, and credits. Run a detailed tax projection before the wedding.
9. What if there was domestic violence in our first marriage?
Do not remarry without extensive professional intervention. A licensed therapist experienced in domestic-violence dynamics can help assess whether genuine, sustained change has occurred. Safety plans and professional guidance are essential—not optional.
10. Will our health insurance change?
Possibly. You may gain access to your spouse’s employer-sponsored plan, but you may also lose individual coverage advantages or subsidies you currently receive. Review both options before the wedding.
11. What is the success rate of remarrying the same person?
Research indicates that the overall divorce rate for second marriages is higher than for first marriages, and remarriages to the same person tend to succeed only when the couple has substantively addressed the original problems. Couples who engage in counseling and create structured agreements report better outcomes, though specific success-rate statistics vary across studies.
12. How long should we wait before remarrying each other?
There is no universal answer, but relationship professionals generally recommend a minimum reconciliation period—often at least one to two years of sustained, healthy interaction including counseling—before remarrying. Some states also impose mandatory waiting periods after a divorce before either party can legally remarry.
15. CONCLUSION
Remarrying your ex-spouse is not a legal reset button. It is a new marriage with old history, and it creates a financial and legal situation that differs from both your first marriage and from marrying someone new.
The most important actions before remarrying your ex:
- Review your divorce decree and understand what was permanently divided.
- Calculate the financial impact—especially alimony termination, tax changes, and benefit losses.
- Execute a prenuptial agreement with independent legal counsel for each spouse.
- Update your will, beneficiary designations, and estate plan immediately.
- Work with a therapist to honestly assess whether the patterns that ended your first marriage have genuinely changed.
The biggest mistakes to avoid:
- Assuming remarriage “undoes” the divorce.
- Ignoring the loss of alimony or benefits.
- Failing to get a prenuptial agreement because it “feels wrong” to ask.
- Skipping estate-plan updates and leaving outdated beneficiary designations in place.
- Remarrying before the emotional work is done.
What varies by jurisdiction: State laws govern property classification, alimony termination, waiting periods, prenuptial-agreement enforceability, estate rights, and many other issues discussed in this article. The general principles here apply broadly, but the specific rules in your state may differ. Consult a family-law attorney in your jurisdiction before making final decisions.
Your next step: If you are seriously considering remarrying your ex-spouse, start with the checklist above. Address the legal and financial realities first—they are the ones that can cost you the most if overlooked. Then invest the time in the emotional preparation that gives your second marriage the best chance of lasting.
17. AUTHOR BIO
About DivorceProLaw.com
DivorceProLaw.com is an educational resource covering divorce, family law, financial recovery, relationships, and life after separation. Its content is designed to help readers understand complex issues and identify appropriate next steps.
18. EDITORIAL DISCLAIMER
Disclaimer: This article provides general educational information and is not a substitute for individualized legal, financial, tax, estate-planning, or mental-health advice. Laws, procedures, and financial rules vary by jurisdiction and individual circumstances. Remarriage involves legal and financial consequences that depend on your specific situation and the laws of your state. Consult a qualified professional in your jurisdiction when your situation requires personalized guidance.
19. SOURCES & REFERENCES
- American Bar Association — Family Law Section
https://www.americanbar.org/groups/family_law/
Referenced for general spousal support principles and family-law standards that govern alimony termination and remarriage. - Internal Revenue Service — Topic No. 452, Alimony and Separate Maintenance
https://www.irs.gov/taxtopics/tc452
Referenced for guidance on the tax treatment of alimony payments, including the distinction between pre-2019 and post-2018 divorce agreements. - Social Security Administration — What Every Woman Should Know (Publication No. 05-10084)
https://www.ssa.gov/pubs/EN-05-10084.pdf
Referenced for rules governing Social Security spousal and survivor benefits eligibility upon remarriage. - United States Courts — Court Website Links
https://www.uscourts.gov/about-federal-courts/court-website-links
Referenced as a resource for locating state and local court websites to research jurisdiction-specific marriage, divorce, and remarriage requirements.